EU Ifr Ifd Class2 Kfactor Prudential
IFR Class 1 (EUR 30B) & Class 1-Minus (EUR 15B) Systemic ECB Thresholds
Proprietary dealers and underwriters reaching EUR 30 billion in EU group assets must convert into ECB-supervised CRR credit institutions, while EUR 15B-30B firms apply full bank RWAs as Class 1-Minus.
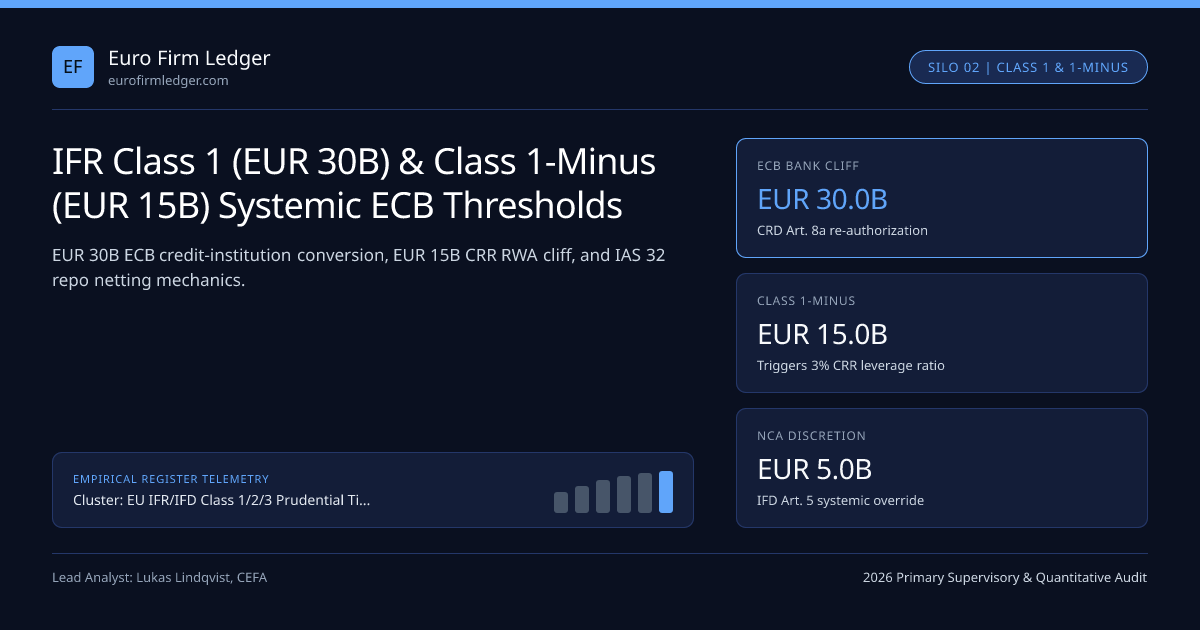
Post-Brexit relocation of global investment-banking trading books into Frankfurt, Paris, Amsterdam, and Dublin prompted EU co-legislators to insert Article 62 of Regulation (EU) 2019/2033 and Article 8a of Directive 2013/36/EU (CRD): any investment firm authorized for MiFID II Annex I Section A(3) (dealing on own account) or A(6) (underwriting/placing on a firm commitment basis) whose consolidated EU/group assets equal or exceed EUR 30 billion ceases to be a regular investment firm by law and must apply for authorization as a Class 1 credit institution under direct European Central Bank Single Supervisory Mechanism (SSM) supervision. Immediately beneath that ceiling sits Class 1-Minus (IFR Article 1(2)), capturing A3/A6 firms between EUR 15 billion and EUR 30 billion under full CRR/CRD bank risk-weighted asset rules without requiring a banking deposit license.
Within our EU IFR/IFD prudential capital guide and the IFR/IFD prudential hub, tracking the 12-month rolling asset average under Commission Delegated Regulation (EU) 2021/2153 is mission-critical for large principal market makers, broker-dealer subsidiaries of non-EU investment banks, and clearing-house liquidity providers.
Statutory Mechanics of CRD Article 8a (EUR 30B) and IFR Article 1(2) (EUR 15B)#
Unlike agency asset managers—which can manage EUR 500 billion of off-balance-sheet client UCITS or discretionary mandates without ever triggering Class 1 because only A(3) dealing on own account and A(6) firm-commitment underwriting count—balance-sheet market makers trigger systemic reclassification through three distinct pathways:
- Standalone or EU-Group EUR 30B Gate (CRD Art. 4(1)(1)(b)(i)-(ii)): Either the individual firm's 12-month average total assets reach EUR 30 billion, OR the individual firm is under EUR 30 billion but belongs to a group whose combined EU-established A3/A6 undertakings hold >= EUR 30 billion in total assets.
- Global EUR 30B Third-Country Sub-Consolidation Gate (CRD Art. 4(1)(1)(b)(iii)): Where an EU A3/A6 subsidiary belongs to a third-country group (e.g., US, UK, Japanese, or Swiss wholesale groups) whose global A3/A6 assets exceed EUR 30 billion, national supervisors and the ECB assess systemic footprint alongside Intermediate EU Parent Undertaking (IPU, CRD Art. 21b EUR 40B threshold) requirements.
- Class 1-Minus EUR 15B Mandatory & EUR 5B Discretionary Gates (IFR Art. 1(2)(a)-(c) & Art. 5): At EUR 15 billion standalone or combined EU group A3/A6 assets—or at EUR 5 billion where a national supervisor such as BaFin or ACPR invokes systemic-stability discretion under IFR Article 5—the firm remains licensed under MiFID II / WpIG but swaps IFR K-factors for full CRR3 market, credit,FRTB, LCR, and NSFR rules.
Structural Comparison: Class 1 ECB Bank vs Class 1-Minus vs Class 2 Dealer#
| Prudential Feature | Class 1 Credit Institution (>= EUR 30B) | Class 1-Minus Investment Firm (EUR 15B–30B) | Class 2 K-Factor Dealer (< EUR 15B) |
|---|---|---|---|
| Legal Charter | CRD Credit Institution (e.g., UniCredit Bank Austria, Algemene Bank Nederland) | MiFID II / WpIG / Code Monetaire Investment Firm | MiFID II Investment Firm (e.g., B2Prime, CAPEX.com) |
| Primary Prudential Supervisor | ECB SSM Joint Supervisory Team (JST) in Eurozone | National Prudential NCA (BaFin/Bundesbank, ACPR, DNB) | National NCA (CySEC, BaFin, AFM, CSSF) |
| Capital & Leverage Ratios | CRR3 RWA (8% + CCoB/CCyB/O-SII) + 3% Tier 1 Leverage Ratio + MREL/TLAC | CRR3 RWA + 3% Leverage Ratio + BRRD MREL | IFR max(EUR 750k PMR, FOR, KFR); no 3% leverage ratio |
| Liquidity & Funding Ratios | 100% LCR + 100% NSFR + ECB ILAAP | 100% LCR + 100% NSFR (NCA LCR waiver possible only in narrow cases) | IFR Art. 43: >= 1/3 FOR |
| Deposit Taking Permitted? | Optional (only if authorized for CRD Art. 4(1)(1)(a) deposits) | Prohibited (cannot take public cash deposits) | Prohibited (client money segregated under MiFID Art. 16(9)) |
Commodity & Emission-Allowance Dealer Carve-Out and Repo Netting Impact#
Under Commission Delegated Regulation (EU) 2021/2153, monthly total assets are measured using the carrying amounts under the applicable accounting framework (IFRS or national GAAP), including derivatives gross positive fair value and reverse-repo receivables unless IFRS/GAAP balance-sheet netting criteria (IAS 32.42) are strictly met. Because matched-book sovereign bond repo desks carry huge gross balance sheets under IFRS, Eurozone primary dealers clear German Bund and French OAT repos through central counterparties (Eurex Clearing / LCH SA) to satisfy IAS 32 offsetting and avoid tripping the EUR 15B / EUR 30B thresholds prematurely.
- (1 / 12) * Sum_{m = t-11}^{t} [
- AssetsIFRSGrossm - EligibleCCPIAS32NettedReposm + EUAffiliateA3A6Assets_m
- ]
- CapitalStepUpFromClass2ToClass1Minus (DeltaCET1_EUR) =
- max(0.070 * RWACRR3FRTB, 0.030 * LeverageExposureMeasure_CRR) - (0.56 * max(750000, FOR, KFR))
- Where:
- 0.070 * RWACRR3FRTB = 4.5% CRR CET1 minimum + 2.5% Capital Conservation Buffer (excluding CCyB/P2R)
- 0.030 * Leverage_Exposure = Binding 3.0% Tier 1 CRR Leverage Ratio on non-risk-weighted exposure
- 0.56 * max(...) = Previous Class 2 IFR Article 9 minimum CET1 floor
- Worked Principal Fixed-Income & Equity Market Maker Crossing EUR 15B Threshold:
- Gross Balance Sheet (12M avg) = EUR 16.2B; Leverage Exposure Measure = EUR 17.5B; CRR3 RWA = EUR 5.8B
- Prior Class 2 KFR (K-CMG + K-DTF + K-TCD) = EUR 195,000,000 -> Class 2 CET1 floor = EUR 109,200,000
- New Class 1-Minus Tier 1 Leverage Floor = 0.030 * 17,500,000,000 = EUR 525,000,000
- New Class 1-Minus CET1+CCoB Floor = 0.070 * 5,800,000,000 = EUR 406,000,000
- Binding Tier 1 / CET1 Step-Up = 525,000,000 - 109,200,000 = +EUR 415,800,000 additional Tier 1 capital!
Capital Step-Up Math Crossing the EUR 15B CRR Leverage Boundary#
Once an algorithmic or repo dealer crosses EUR 15 billion, non-risk-weighted balance-sheet leverage replaces margin-based K-CMG as the binding constraint.
Operational Continuity During CRD Article 8a Re-Authorization#
Under CRD Article 8a(3) and Commission Delegated Regulation (EU) 2022/2579, an investment firm breaching the EUR 30 billion 12-month rolling average must submit its credit-institution authorization dossier at the latest on the day when the 12-month average reaches EUR 30 billion, yet is explicitly authorized by statute to continue carrying on its A(3) and A(6) MiFID activities while the ECB and national supervisor process the application—preventing disruptive trading-desk freezes while transitioning onto Single Resolution Board (SRB) MREL bail-in schedules and CRD V bonus caps (contrasted with IFD Articles 30-32 remuneration).
Frequently asked questions
Can a EUR 200 billion discretionary asset manager be forced to become a Class 1 ECB bank?
No. Off-balance-sheet client Assets Under Management (AUM) or safeguarded custody assets (ASA) do not count toward the EUR 15B or EUR 30B balance-sheet tests, and pure A(4) portfolio managers lacking A(3) dealing or A(6) underwriting permissions are statutorily exempt from Class 1 and Class 1-Minus.
Can a Class 1 systemic investment firm accept retail cash deposits once re-chartered under CRD Article 8a?
Not automatically. CRD Article 4(1)(1) splits credit institutions into (a) deposit-taking banks and (b) EUR 30B+ systemic A3/A6 dealers. A CRD Article 8a authorization covers wholesale dealing and underwriting unless the firm separately applies for deposit-taking permissions and joins a DGSD deposit guarantee fund.
Under what conditions can a national regulator impose CRR banking rules on a EUR 6 billion investment firm?
Under IFR Article 1(2)(c) and IFD Article 5, if an A(3)/A(6) firm has consolidated assets of at least EUR 5 billion, its competent authority may apply CRR requirements where the firm’s size, systemic interconnectedness, or cross-border clearing footprint poses financial-stability risks.
How long must a Class 1-Minus firm stay below EUR 15 billion before returning to Class 2 K-factor rules?
Under IFR Article 1(4), once an investment firm crosses the EUR 15 billion threshold into CRR supervision, it can revert to IFR Class 2 K-factors only after its consolidated monthly assets remain continuously below EUR 15 billion over a full consecutive 12-month period.
Publication record
- Published
- 14 November 2026
- Updated
- 14 November 2026
- Author
- Lukas Lindqvist, CEFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 4 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Lukas Lindqvist, CEFA. (2026, November 14). IFR Class 1 (EUR 30B) & Class 1-Minus (EUR 15B) Systemic ECB Thresholds. Euro Firm Ledger. https://eurofirmledger.com/bulletins/ifr-class-1-30b-15b-systemic-investment-firm-ecb-crr-thresholdsFurther Institutional Analysis & Briefings
EU Ifr Ifd Class2 Kfactor Prudential
IFR Article 12 Class 3 SNI Thresholds: All 10 Quantitative Tests & Transition LagsEU Ifr Ifd Class2 Kfactor Prudential
IFD Article 9 Initial & Permanent Minimum Capital: EUR 75k, 150k & 750k TiersEU Ifr Ifd Class2 Kfactor Prudential
IFR Article 13 Fixed Overheads Requirement (FOR) & RTS 2022/1455 DeductionsEU Ifr Ifd Class2 Kfactor Prudential
IFR Risk-to-Client (RtC) Formulas: K-AUM, K-CMH, K-ASA & K-COH CoefficientsEU Ifr Ifd Class2 Kfactor Prudential
IFR Risk-to-Market (RtM): K-NPR CRR Standardized Rules vs K-CMG 1.3x Clearing MarginEU Ifr Ifd Class2 Kfactor Prudential
IFR Trading Counterparty Default (K-TCD): 1.2 Alpha, Potential Future Exposure & CVAEU Ifr Ifd Class2 Kfactor Prudential
IFR Daily Trading Flow (K-DTF): Principal Execution Risk & RTS 2022/26 Stress ScalarsEU Ifr Ifd Class2 Kfactor Prudential
IFR Part Four Concentration Risk (K-CON): 25% Own-Funds Limit & 200%–900% MultipliersEU Ifr Ifd Class2 Kfactor Prudential
IFR Article 9 Own-Funds Composition: 56% CET1, 75% Tier 1 & CRR Deduction RulesEU Ifr Ifd Class2 Kfactor Prudential
IFR Article 43 Liquid Assets Requirement: One-Third FOR, HQLA Haircuts & Cash RulesEU Ifr Ifd Class2 Kfactor Prudential
IFR Articles 7 & 8 Investment Firm Groups: Prudential Consolidation vs Group Capital TestEU Ifr Ifd Class2 Kfactor Prudential
IFD Article 24 ICARA Process: Internal Harm-Matrix Capital, Stress Testing & Wind-Down Plans
Euro Firm Ledger Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.